
People think of these as college accounts. For a family with money to pass down, they do more than that. A 529, a UTMA, and a UGMA are three ways to move wealth to your kids and grandkids. They handle taxes and control very differently, and that difference is the whole decision.
Every grandparent wants to be generous. Almost none of them want to be reckless.
The Hansens are a good example. Forty years of steady saving left them comfortable, with three grandchildren and a simple goal: give each of them a head start. Two things make them hesitate. They want to move money out of their estate while they can. And they are not sure they want a 19-year-old with sudden access to a six-figure account.
Generosity and control. Most families want both. The account you pick decides how much of each you get.
Three accounts, one decision
A 529, a UTMA, and a UGMA all let you invest money for a child. They differ on two things: what the money can be used for, and who controls it, and until when. Everything else is detail. Get those two right and you have made the decision.
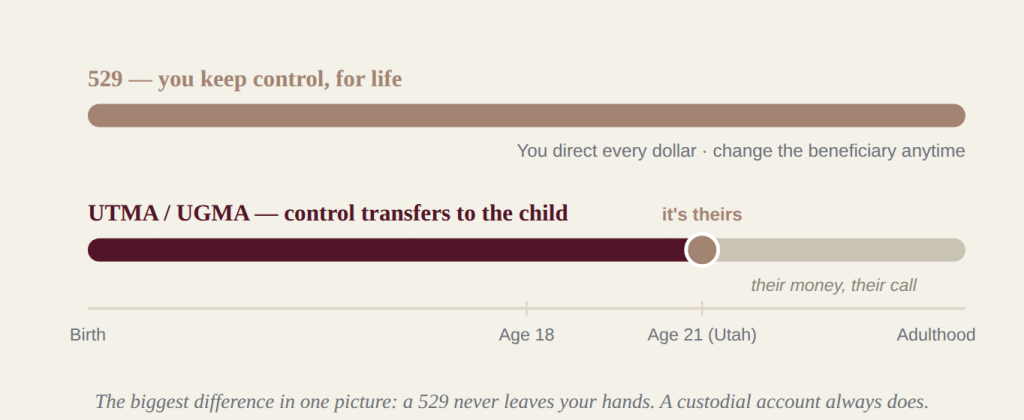
A 529 points at one thing, which is education. You keep control the whole way, and you can change who the money is for. A UTMA or UGMA can go toward anything that benefits the child, but the control is temporary. On a set birthday, the account becomes the child’s, and what they do with it is their call.
One way to keep it straight: a 529 is money you steer. A UTMA or UGMA is money you hold until the child is old enough to steer it themselves.
529 vs. UTMA vs. UGMA, side by side
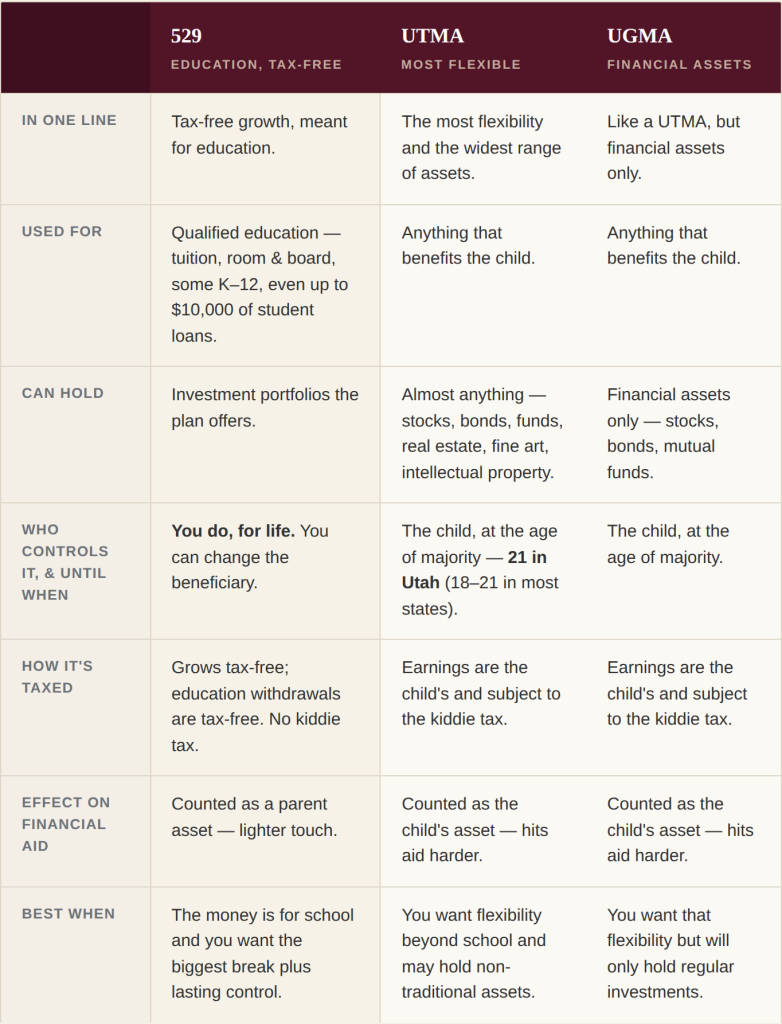
Here is how the three compare on the things that actually matter to a family.
The bigger reason to care: taxes and your estate
Used well, these accounts do more than save for college. They move money out of your estate and cut the tax on it. That is the conversation the Hansens actually needed to have.
Gifting: moving money out of your estate
Start with the gift. In 2026 you can give any one person up to $19,000 a year with no tax and no return to file. A married couple can give $38,000 to each grandchild. The Hansens have three grandchildren, so they could move $114,000 out of their estate this year, then do it again next year.
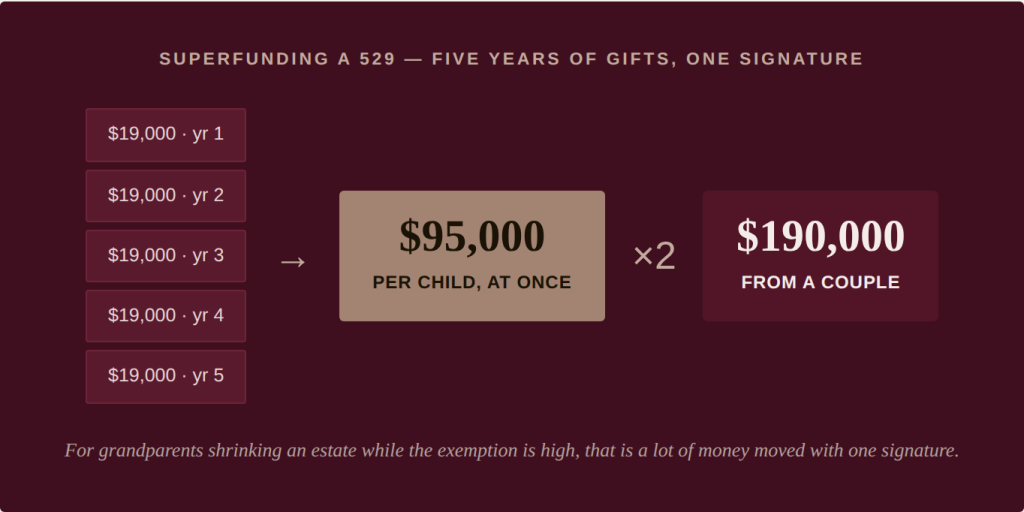
A 529 adds one move the others do not: superfunding. You can put five years of gifts in at once, up to $95,000 per child or $190,000 from a couple, without touching your lifetime exemption.
Control: where the accounts really differ
A 529 stays yours. If a grandchild skips college, you move the money to another one. A custodial account works the other way. On the child’s 21st birthday in Utah, it is legally theirs. They can put it toward tuition or a boat, and you do not get a vote. For some families that is fine. For others it is a dealbreaker. Either way, it is better to know before you fund the account than after.
Taxes: the kiddie tax, in plain numbers
Money in a custodial account earns income every year, and that income is taxed under the kiddie tax. Here is how a child’s unearned income is treated in 2026:

A 529 avoids this. The money grows without throwing off taxable income each year, and withdrawals for school come out tax-free. Over eighteen years, for a family in a high bracket, that gap adds up to real money.
So which one?
There is no universal right answer. There is a right answer for what you are trying to do.
- 529 — The money is for school and you want the biggest tax break with full control.
- UTMA — You want flexibility beyond school and may hold real estate, a business interest, or art.
- UGMA — You want that flexibility but will only ever hold regular investments.
For a lot of families with money, the answer is more than one account: a 529 for school, a custodial account for the rest, kept small enough to stay under the kiddie-tax line.
The hard part isn’t opening the account
Opening any of these takes ten minutes. Using them well is the hard part, because they do not sit off on their own. The right move depends on your estate plan, how much you are gifting, which assets you put in, and how the income shows up on your tax return. The work is not picking an account. It is fitting it into everything else, then actually doing it: opening the accounts, moving the assets, naming the beneficiaries, and keeping the tax picture clean each year.
That coordination is what a Private Wealth Review is for
We start with what you want to pass on, who gets it, and when. Then we build the plan that does it with the least tax and the least friction, and we handle the paperwork to put it in place. No commissions, and no products we are paid to push. A flat 1% fee, and a legal duty to act in your family’s interest.
This article is general information, not tax or legal advice. Gift, estate, and kiddie-tax figures are 2026 federal amounts and change over time; state rules, including the age of majority, vary. Your situation is specific, which is what the review is for.
